W | Wulf Collaboration
Incentives table Coldwell Banker Realty 614-483-2044

179 communities  |  23 builders  |  Offers checked Oct 22, 2026

The New Build Search Guide  |  Central Ohio

Imagine it brand new


Picture the first morning in a home nobody has lived in before you. Every new home community around Columbus is right here, with the homes, the prices and what each builder is offering this month, and me on your side from the first model visit to the day you get your keys.

Representative footage of new construction

Presented by Nick Wulf  |  Coldwell Banker Realty

Nobody has lived here before you. Every first in this home is yours.

That is what brand new feels like. Fresh paint, appliances nobody has used, and a home built to today's building codes, with most builders standing behind it with a warranty. You choose the homesite, the floor plan and the finishes, or you walk into one that's ready this season. Around Columbus right now there are 179 new home communities from 23 builders, and this guide puts every one of them side by side.

179
Communities
23
Builders
481
Floor plans
406
Move-in ready homes
$230K to $1.8M
Starting prices

Start with the home

What kind of new home are you picturing?

Tap a style to see every community that builds it, with starting prices and what each builder is offering right now.

Looking for a townhome? 28 communities build them.  Representative photos of new construction, not a specific home, builder or community.

Downtown Columbus skyline across the river, with an arched bridge
Downtown Columbus

01   The location

It all comes down to location

Before the floor plan and before the finishes, there's the map. The drive to work, the grocery store, the parks and trails nearby, the school district that serves the homesite, and what's planned on the land next door. Columbus is growing in every direction, and each side of town has its own character and its own price points.

  • West60 communities from $230K. Plain City, Hilliard, Marysville, Dublin, Galloway
  • North55 communities from $285K. Delaware, Lewis Center, Powell, Sunbury, Westerville
  • East36 communities from $268K. Canal Winchester, Pickerington, Pataskala, Etna, New Albany
  • South28 communities from $230K. Grove City, South Bloomfield, Circleville, Commercial Point, Ashville
NorthSouthWestEastI-270I-70I-71US 33DowntownPlain City 32Plain City: 32 communitiesDelaware 16Delaware: 16 communitiesGrove City 13Grove City: 13 communitiesLewis Center 12Lewis Center: 12 communitiesPowell 10Powell: 10 communitiesSunbury 9Sunbury: 9 communitiesCanal Winchester 7Canal Winchester: 7 communitiesHilliard 7Hilliard: 7 communitiesPickerington 7Pickerington: 7 communitiesPataskala 6Pataskala: 6 communitiesMarysville 5Marysville: 5 communitiesWesterville 5Westerville: 5 communitiesDublin 5Dublin: 5 communitiesSouth Bloomfield 4South Bloomfield: 4 communitiesGalloway 4Galloway: 4 communitiesLondon 3London: 3 communitiesEtna 3Etna: 3 communitiesCircleville 3Circleville: 3 communitiesCommercial Point 3Commercial Point: 3 communitiesNew Albany 3New Albany: 3 communitiesNewark: 2 communitiesAshville: 2 communitiesReynoldsburg 2Reynoldsburg: 2 communitiesGalena: 2 communitiesWest Jefferson: 1 communityLithopolis: 1 communityHebron: 1 communityBuckeye Lake: 1 communityWorthington: 1 communityBaltimore: 1 communityLockbourne: 1 communityHeath: 1 communityBlacklick: 1 community
Each dot is a city or town with new home communities in this guide, sized by how many. Tap one to search it. Map not to scale.
A new street of brick and siding homes with fresh sod and new driveways

Representative photo

03   The neighborhood

New streets, new sidewalks, a new walk around the block

Many new communities are planned around walking paths, green space and amenities like pools and clubhouses, and you watch it all take shape. Before you choose a homesite, I'll show you what's built, what's planned and what's coming next door.

04   The build

From the ground up

Building new is a process you can see with your own eyes. Here's what happens between signing and the keys, and where I'm with you at every step.

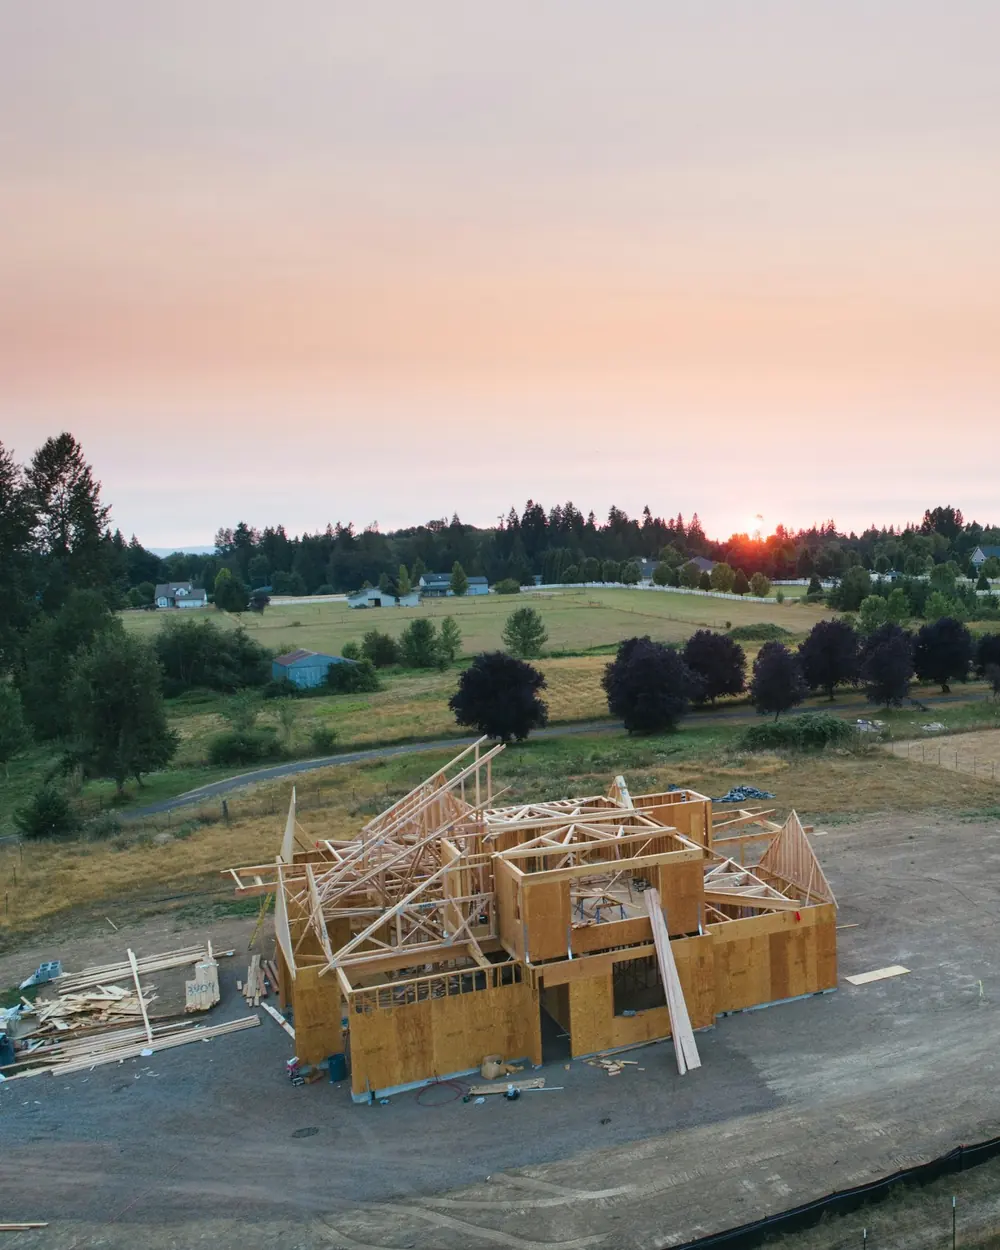
  1. A new home being framed on an open homesite at sunset

    01

    Choose the homesite

    The lot decides the light, the view and the price. I compare homesite premiums, which way the home faces and what's planned around it.

  2. CabinetryQuartzPlank floor TilePaintHardware

    02

    Make your selections

    Cabinets, counters, flooring and fixtures at the design center. This is where budgets drift, so I help you choose what's worth doing now and what you can add later for less.

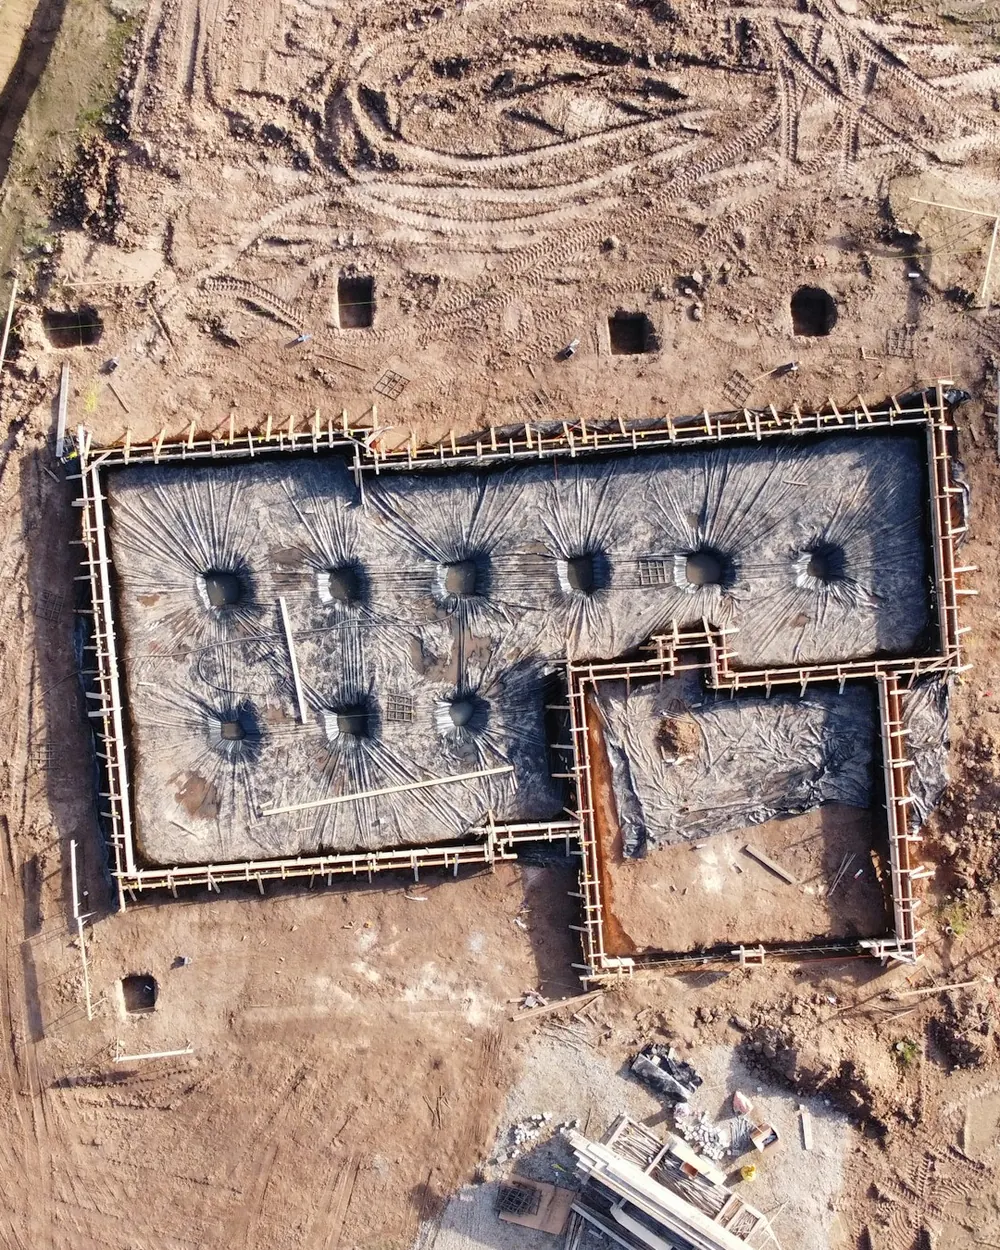
  3. A new home's basement foundation walls from above, ready for framing

    03

    The foundation

    The slab or basement goes in and the home takes its footprint. I keep an eye on the schedule so your closing date stays real.

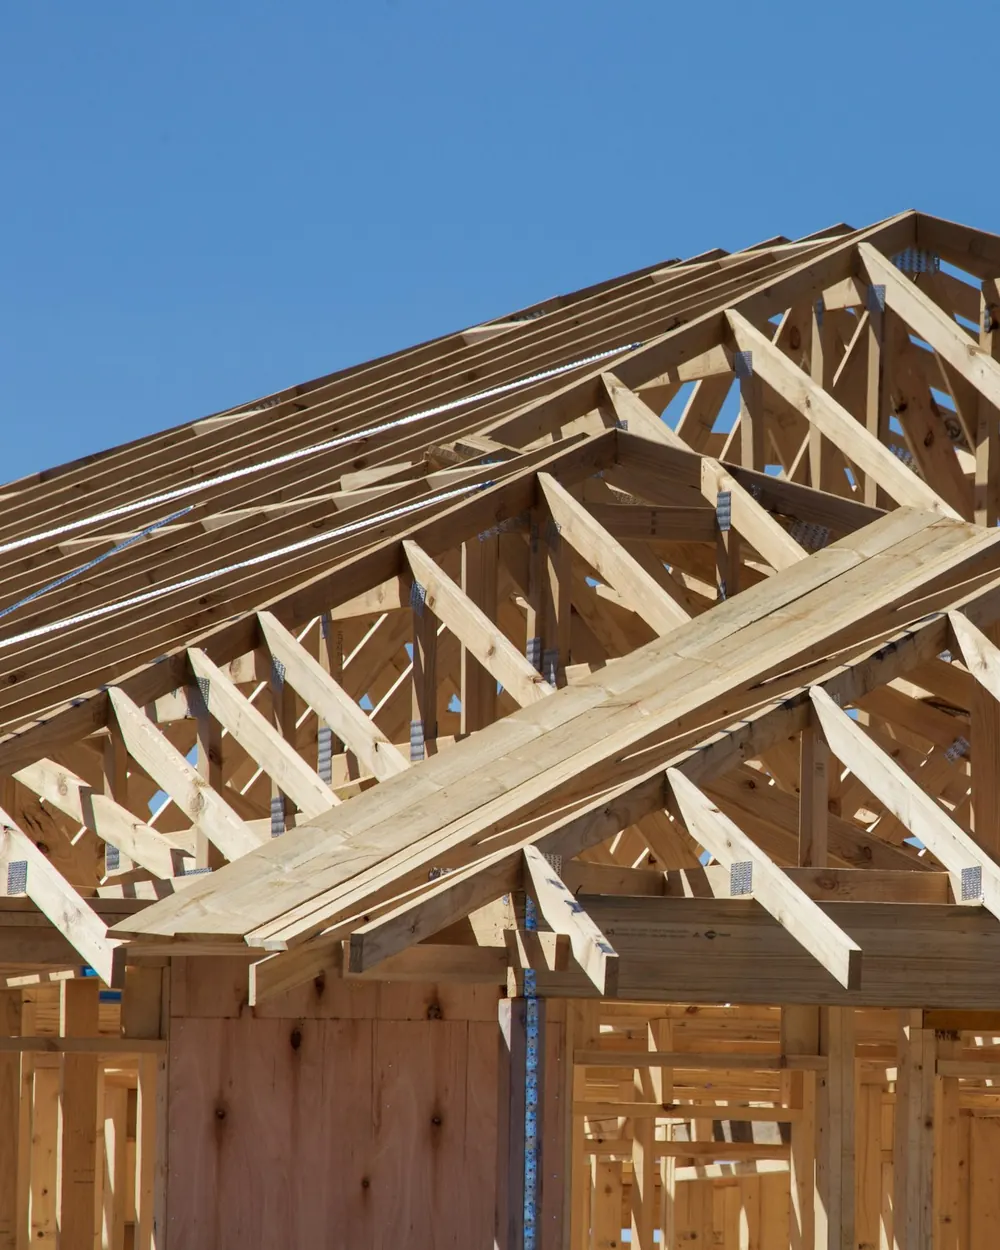
  4. Roof trusses and wall framing going up on a new home against a blue sky

    04

    Framing and house wrap

    The structure goes up fast, and for the first time the rooms have a shape. It's the best day to walk the home and picture the furniture.

  5. 05

    The pre-drywall walk

    Before the walls close, an independent inspector checks framing, wiring, plumbing and ductwork. Problems are easy to fix now and expensive later.

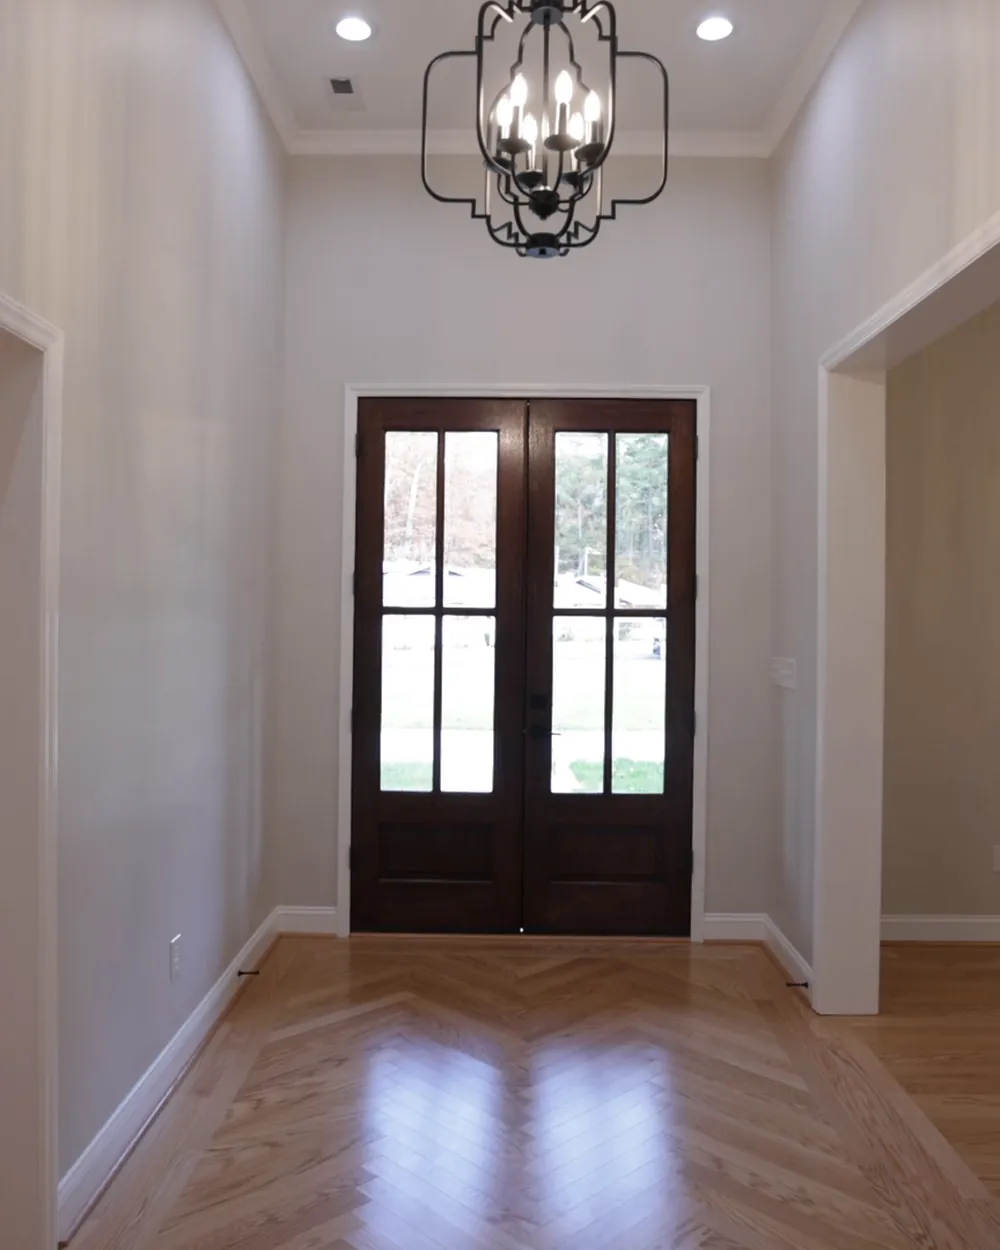
  6. A bright new foyer with hardwood floors, a chandelier and double front doors

    06

    Walkthrough and keys

    We walk every room together, write the punch list and make sure it's finished before closing. Then the door is yours.

Representative photos of new construction, not a specific home, builder or community.

05   The finished home

Then you walk in

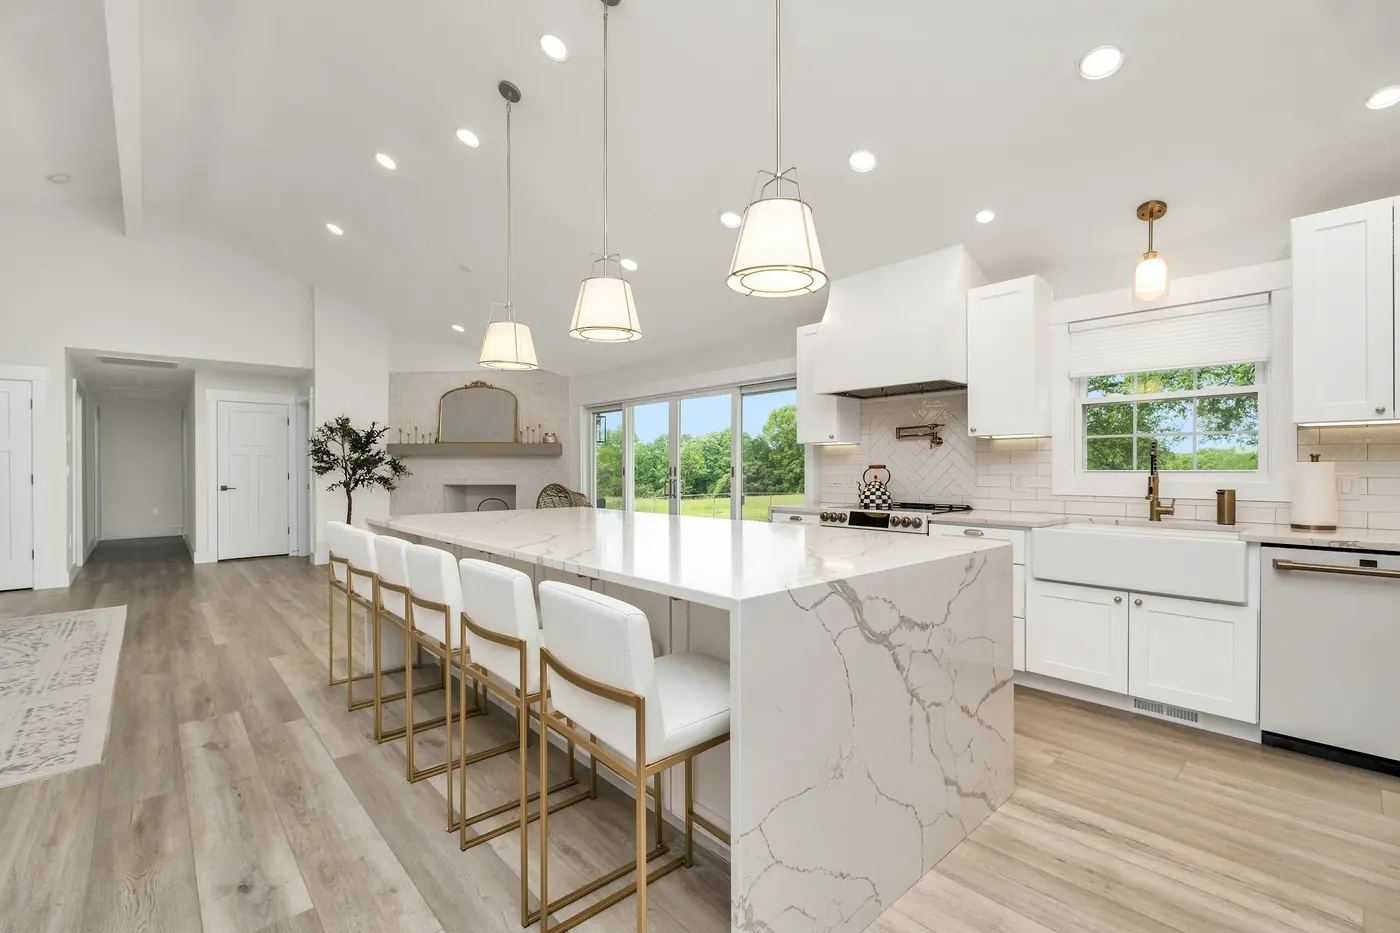
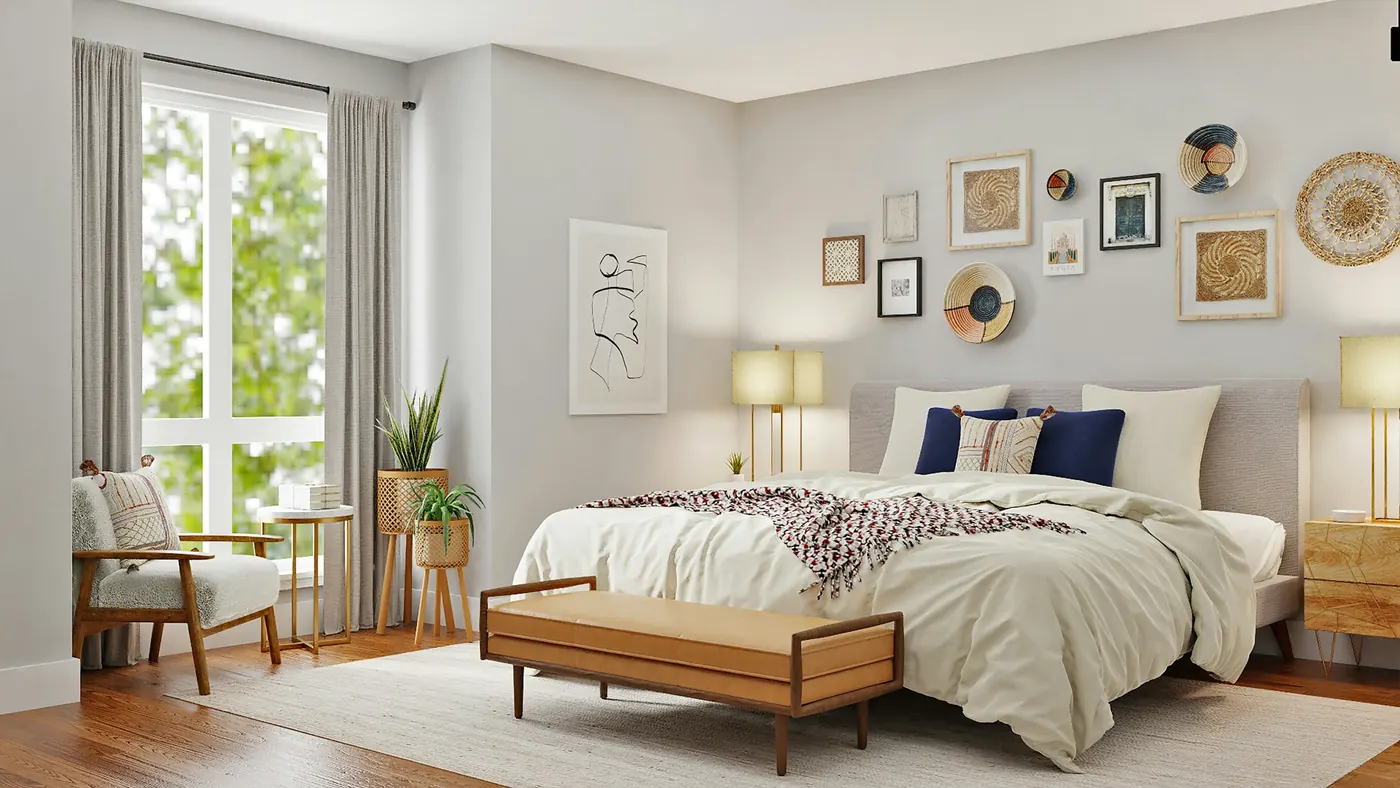
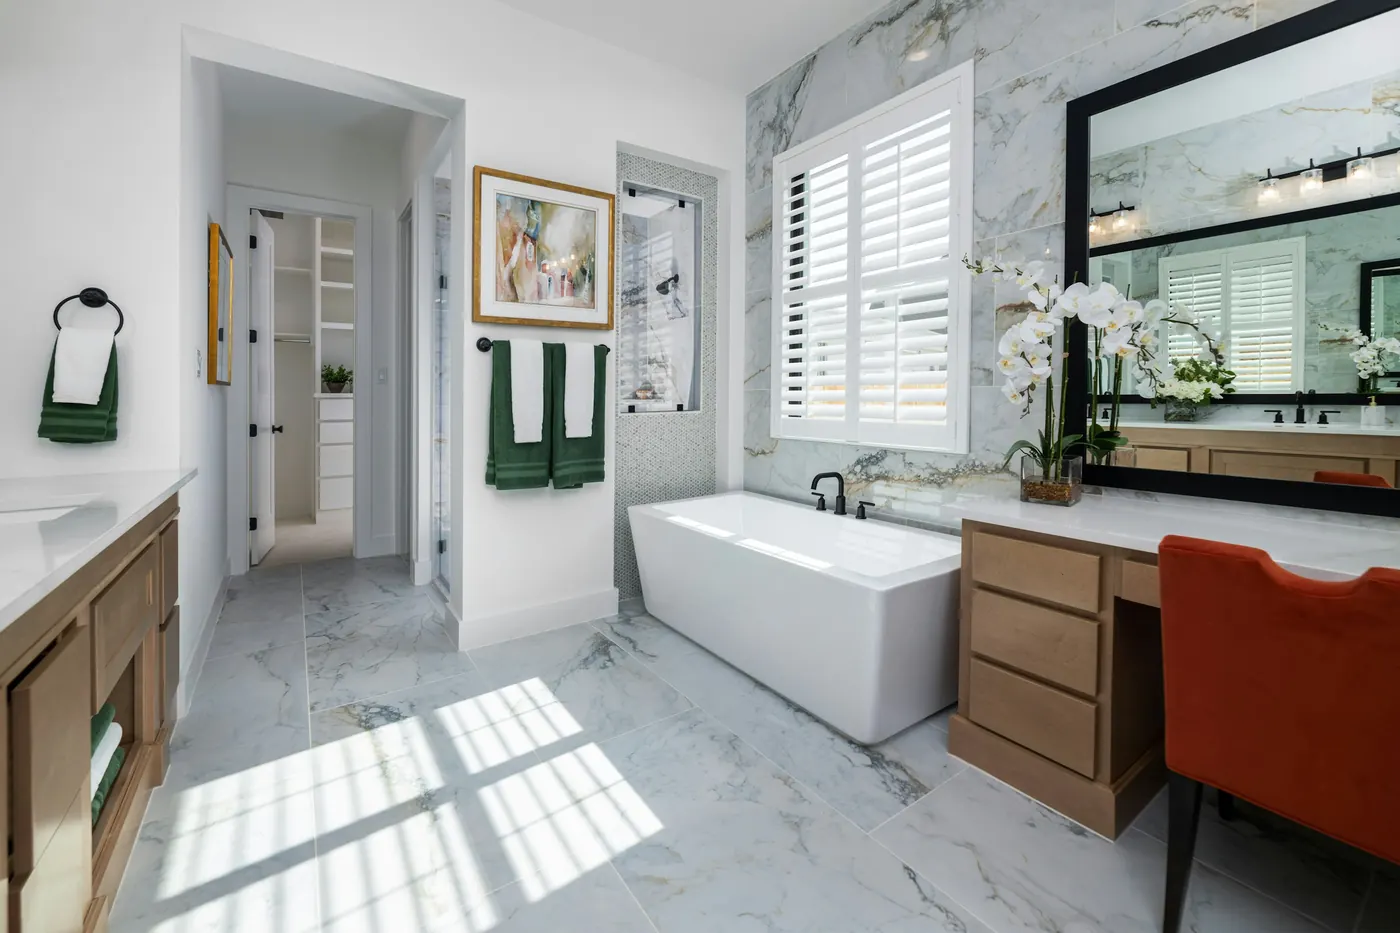
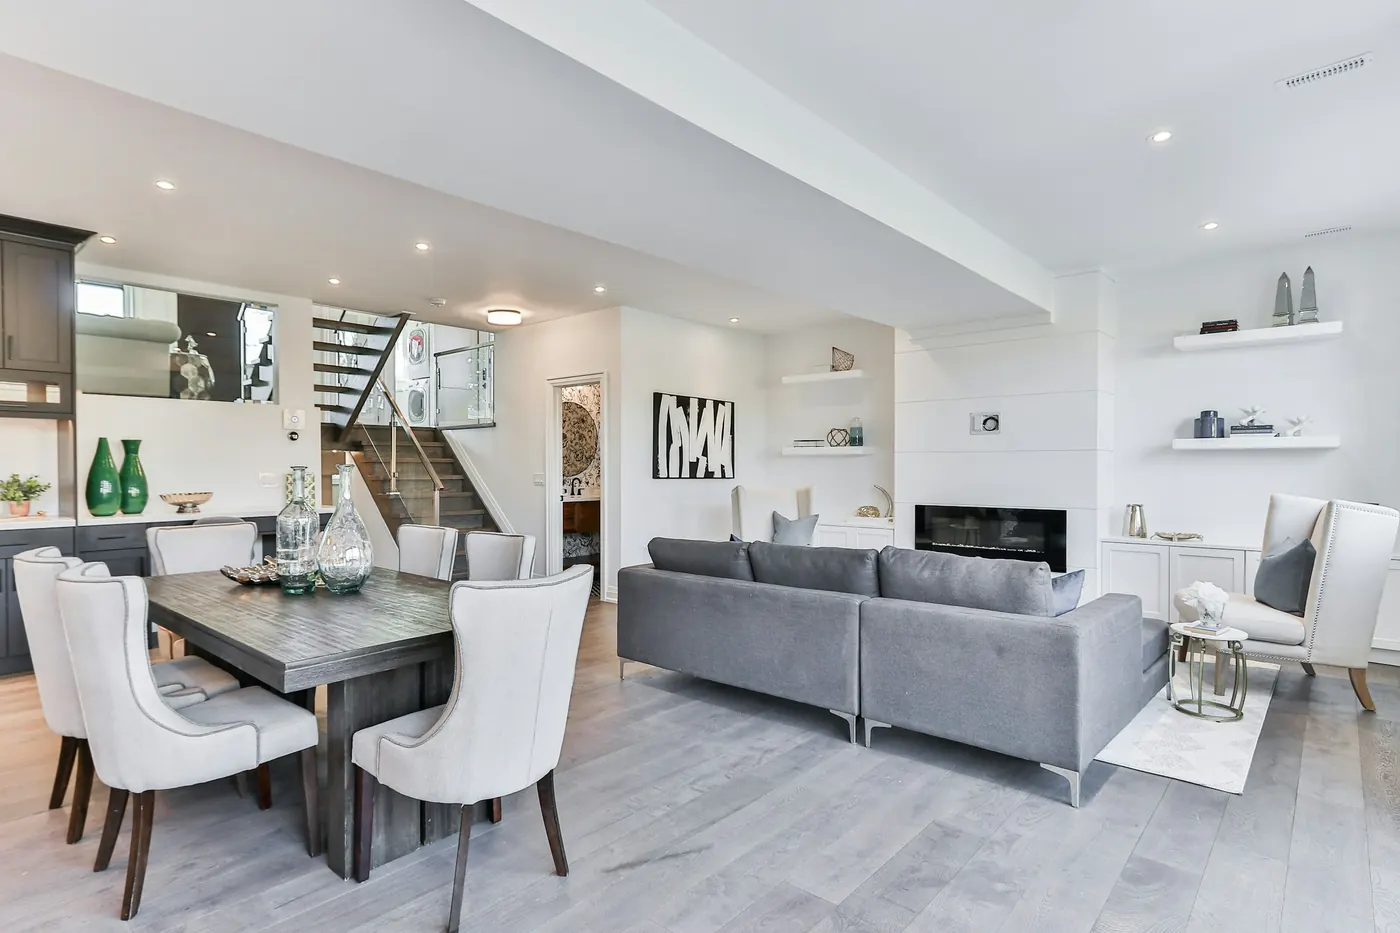
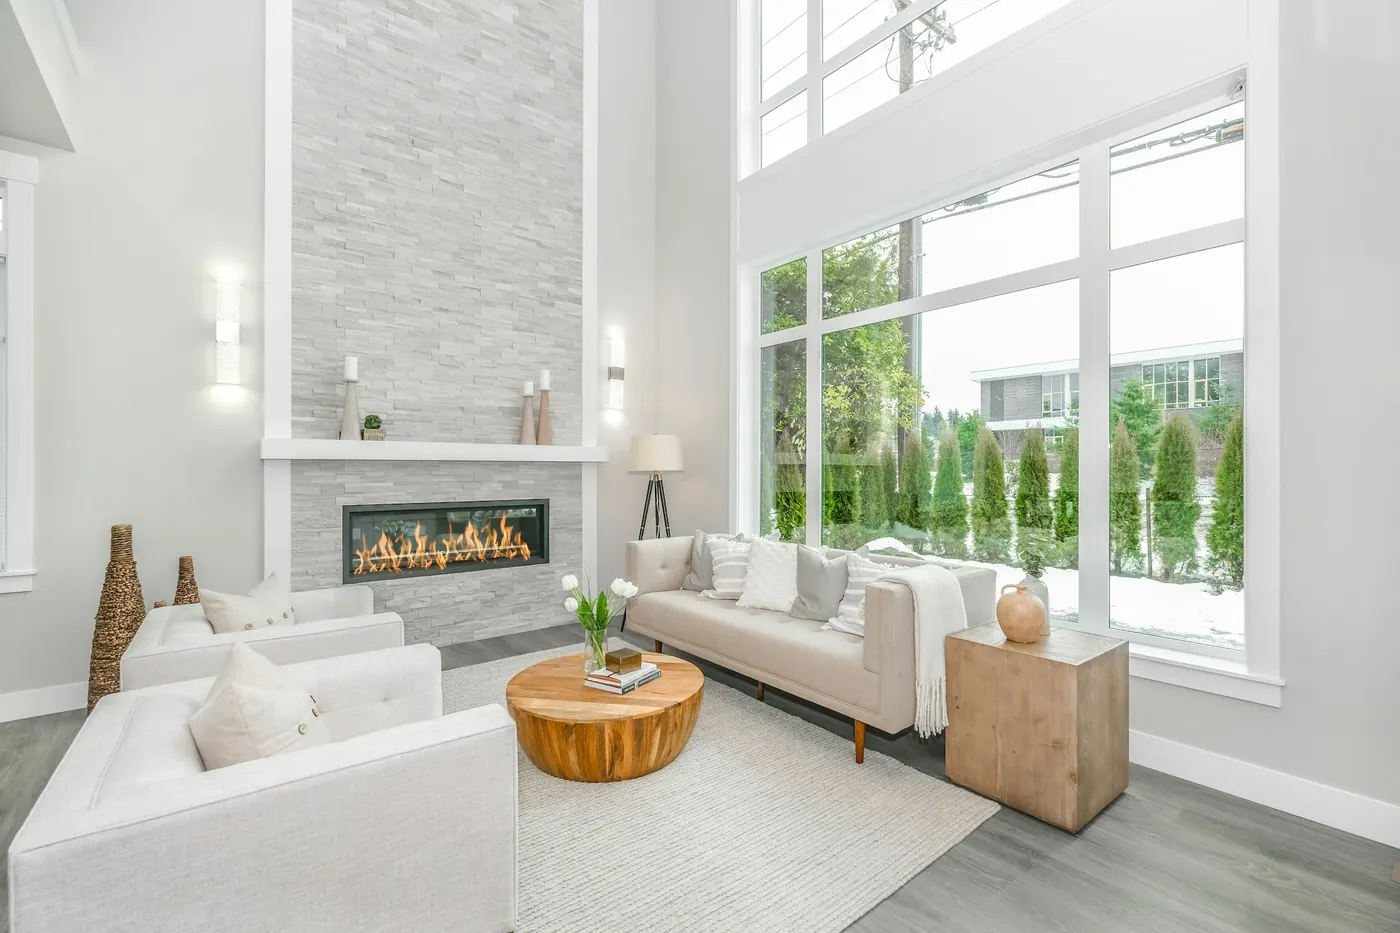
Open kitchens, bright great rooms, primary suites with room to breathe and covered space outside. Builders around Columbus offer finishes like these as standard features or design center options, and I'll help you sort out which is which.

White kitchen with a waterfall quartz island, pendant lights and plank floors

The kitchen

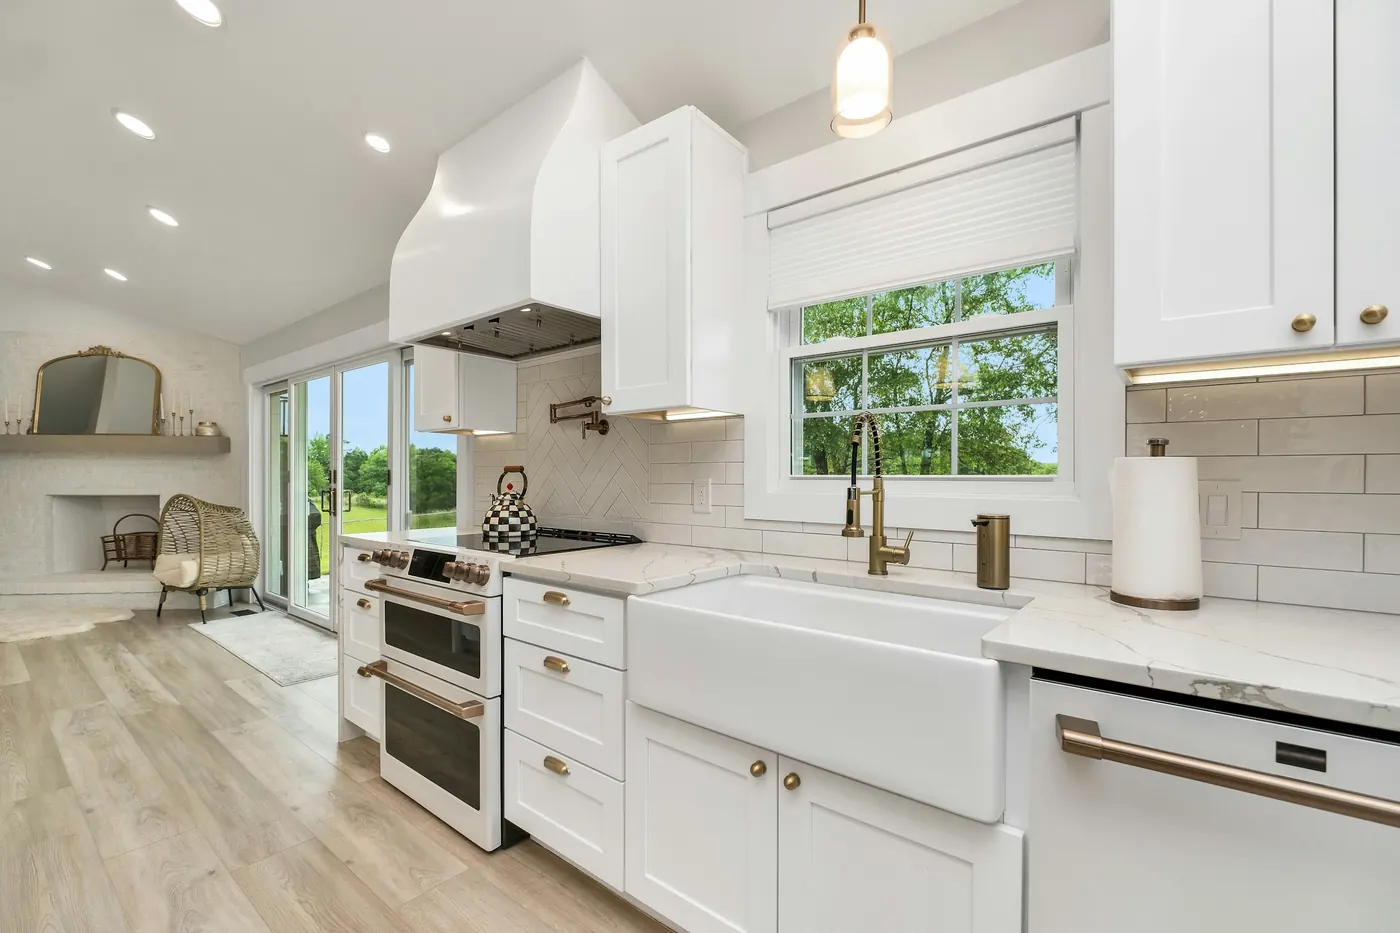
Farmhouse sink below a window, with white shaker cabinets and gold hardware

Farmhouse sink

Primary bedroom with tall windows, a bench and a gallery wall

Primary suite

Primary bath with a freestanding tub, marble tile and a makeup vanity

Primary bath

Open dining and living room with a linear fireplace and a staircase

Dining and living

Great room with a stone fireplace wall and tall windows

Great room

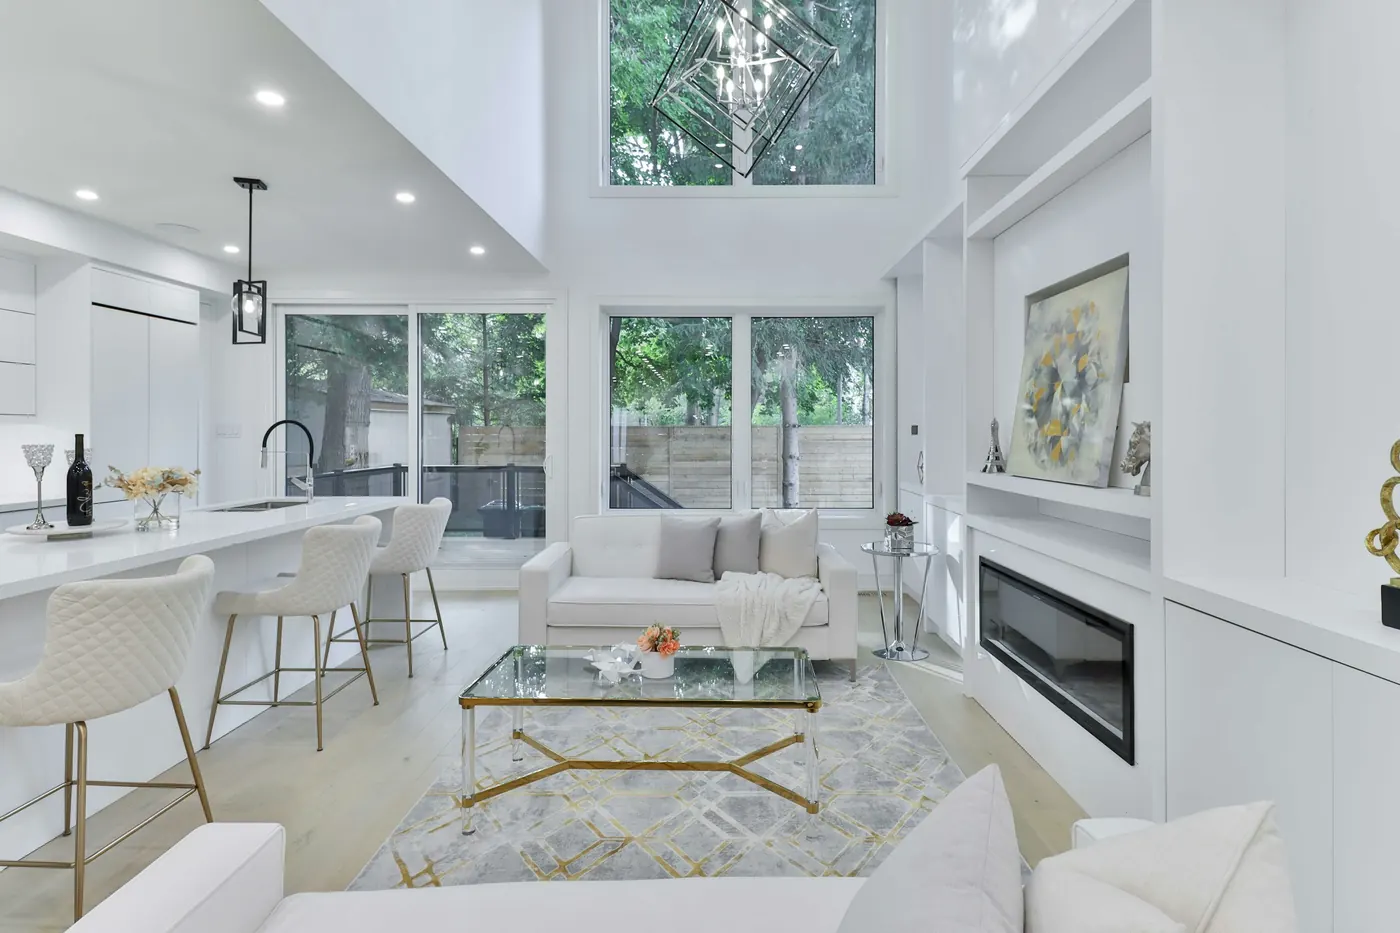
Two-story great room open to the kitchen, with a fireplace

Two-story great room

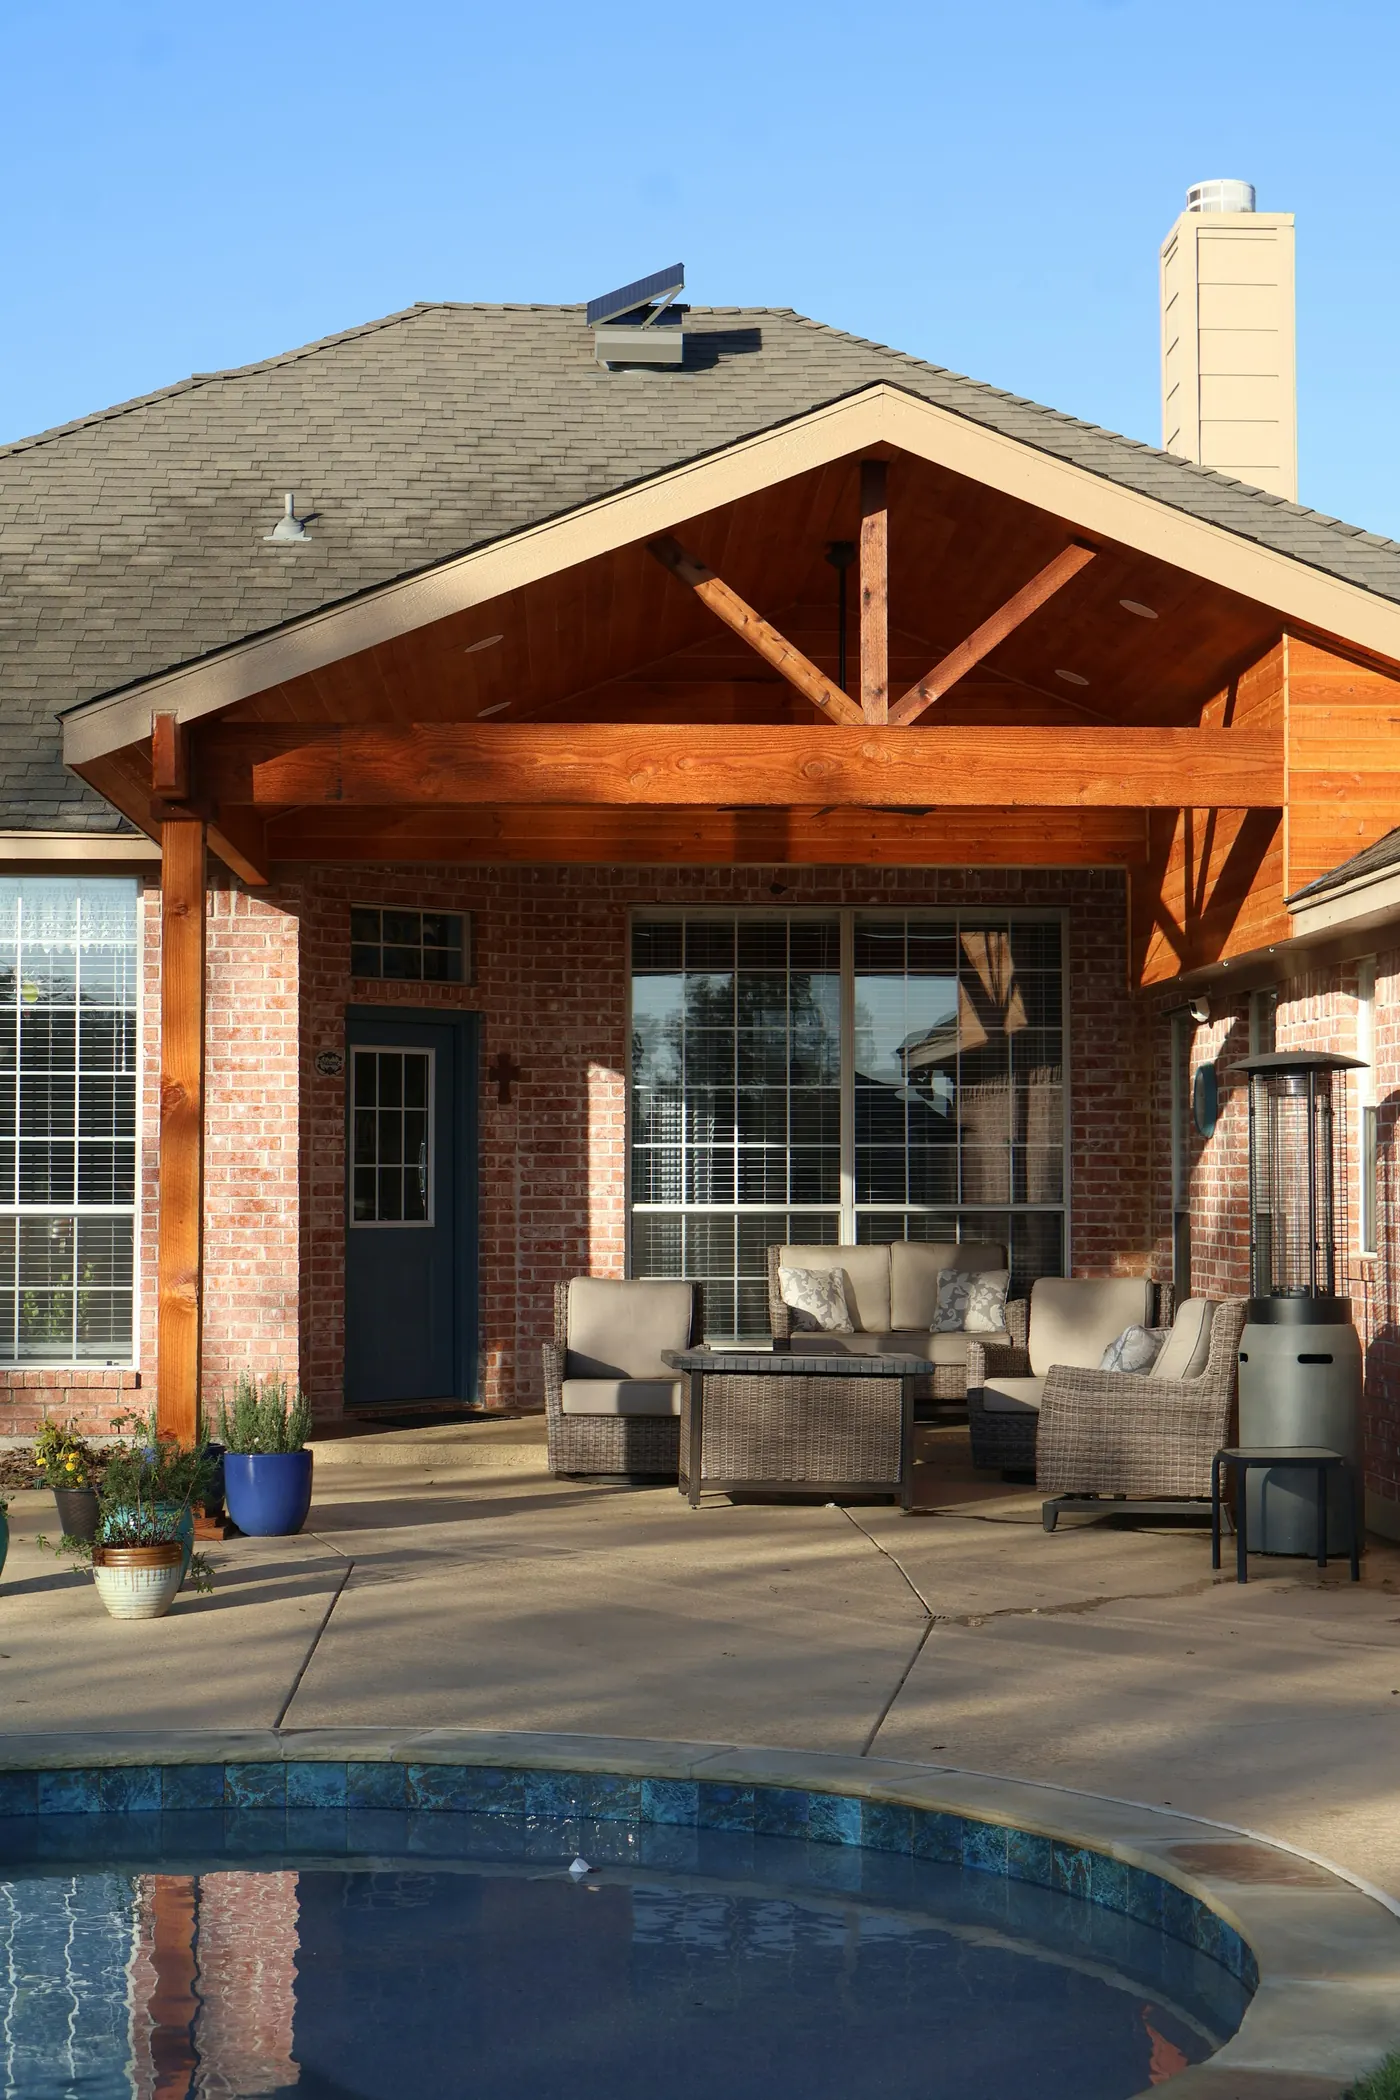
Covered back patio with a timber-framed roof and outdoor seating

Covered patio

Representative photos of new construction, not a specific home, builder or community. Furnishings and decor are not included, and finishes vary by builder, plan and community.

06   The payment

What's a comfortable monthly payment for you?

Start with the payment that feels right, or with a home price, and see the whole picture: principal and interest, taxes, insurance, mortgage insurance and HOA dues. Then see how a builder's rate buydown changes the first years.

$
Loan type
Down payment
%
Loan term

Rate starts at the Freddie Mac weekly average for a 30-year fixed loan, 7.40% (15-year: 6.71%), as of October 15, 2026. It's a reference point, not a quote. Change it to anything you like.

Taxes, insurance and HOA
%
$
$
%

Starting values: Franklin County's median effective property tax rate, 1.69% (Ownwell, April 2026; Delaware, Union, Madison, Fairfield and Licking counties differ). Ohio's average home insurance premium for $400,000 of dwelling coverage, $2,080 a year (NerdWallet, March 2026). Private mortgage insurance usually runs $30 to $70 a month per $100,000 borrowed (Freddie Mac), so 0.60% sits in the middle. FHA uses 0.55% a year plus a 1.75% upfront premium added to the loan (HUD). Add the community's HOA dues when you know them.

Homes up to about

$0

How a builder buydown works

Lower payments in the first years

With a temporary buydown, the builder pays money up front so your rate starts lower and steps up to the full rate. A 2-1 buydown starts two points lower in year one and one point lower in year two. A 1-0 buydown is one point lower for the first year. Here's what it does on the loan above.

YearRatePrincipal and interest

Payment options

Ways to buy at this price

The same home, four ways to finance it. More down means a smaller loan and, at 20%, no private mortgage insurance.

OptionDown paymentEst. monthly

For illustration only. These are estimates from the numbers you enter, not a loan estimate, a quote, an advertisement of credit terms or an offer to lend. Your rate, APR and payment depend on your credit, loan program, down payment, lender fees and the property, and taxes and insurance vary by home and county. The Wulf Collaboration and Coldwell Banker Realty are not lenders. Talk with a licensed lender before you decide.

07   The incentives

Let's break down buyer incentives

Builders compete for buyers with real money. This month it shows up four ways, and the best package usually combines them. I know what each builder is putting on the table, and I ask for more.

35 communities

Closing cost help

Up to $6,500 to $10,000 toward closing costs, usually when you finance with the builder's affiliated lender.

61 communities

Flex cash and design credits

Up to $50,000 to put toward options, upgrades or the homesite premium, depending on the builder and the home.

16 published programs

Rate buydowns

Builder-affiliated lenders are publishing first-year rates from 3.25% (5.821% APR) on select homes. Every program is listed below.

48 communities

Price reductions

Reduced prices on select move-in ready homes, published by the builder and often changing week to week.

Open the incentives table

All 179 communities side by side: closing cost help, flex cash, price cuts and rate programs with APRs. Filter by area, builder and price.

What I negotiate for you

Homesite premiums  where there's room to move
Design options  and which upgrades to skip
Closing date  and rate lock timing
Where a credit works hardest  price, rate or closing costs
The builder's contract  deposits, timelines, what happens if dates move
Inspections  during construction and the punch list before closing

Published builder rate programs

Rates and APRs, exactly as the builders publish them

BuilderProgramRateAPRTerms
M/I Homes2-1 buydown, FHA 30-year fixed3.25% year 1, 4.25% year 2, 5.25% years 3 to 305.821%Select move-in ready homes. New contracts Oct 12 to Nov 8, 2026, closing by Dec 31, 2026, through M/I Financial, LLC. APR example: $535,000 price, 3.5% down, 640 credit score.
M/I Homes2-1 buydown, conventional 30-year fixed3.875% year 1, 4.875% year 2, 5.875% years 3 to 306.131%Same homes and dates. APR example: $535,000 price, 10% down, 720 credit score, mortgage insurance included.
M/I Homes7/6 ARM, conventional4.875% for 7 years, then adjusts every 6 months5.316%Select homes. New contracts Oct 12 to Nov 8, 2026, closing by Nov 30, 2026. APR example: 10% down, 720 credit score. The rate and APR can increase after the fixed period.
M/I HomesLong-term rate lock, conventional 30-year fixed6.25%6.516%Select move-in ready homes closing Jan 4 to May 28, 2027. New contracts Oct 12 to Nov 8, 2026. A 1% lock deposit is due at application, with a float-down if rates drop.
Pulte HomesFirst-year rate, FHA 30-year fixed3.99% first year6.157%Certain move-in ready homes at 11 Columbus communities. Contract on or after Oct 7, 2026 and close by Dec 31, 2026. Pulte's community pages don't show the APR example or the rate after year one; I'll get both for you.
Pulte HomesFirst-year rate, FHA 30-year fixed, Sugar Farms Summit Collection3.25% first year5.984%Certain Summit Collection move-in ready homes at Sugar Farms. Contract on or after Sep 17, 2026 and close by Dec 31, 2026.
Pulte Homes2-1 buydown, conventional 30-year fixed3.75% year 1, 4.75% year 2, 5.75% years 3 to 305.913%Through Pulte Mortgage. Pulte's example: $500,000 price, 10% down, $9,849 buydown fee, 760 credit score. Lock and close by Dec 31, 2026. May vary by community.
Pulte Homes7/6 ARM, conventional4.75% for 7 years, then adjusts every 6 months5.772%Through Pulte Mortgage. Pulte's example: $500,000 price, 10% down, 760 credit score. Lock and close by Dec 31, 2026. The rate and APR can increase after the fixed period.
Del Webb7/6 ARM, conventional4.50% for 7 years, then adjusts every 6 months5.579%Published on Del Webb's Columbus page through Pulte Mortgage, locked and closed by Feb 28, 2027. Example: $500,000 price, 10% down, 760 credit score. I confirm it applies to Explore homes before you sign. The rate can increase after year 7.
Fischer Homes5/1 ARM, FHA 30-year4.99% for the first 5 years6.599%Select move-in ready homes that can close by Nov 30, 2026, through Victory Mortgage, while the lender's allocation lasts. Example: 3.5% down, 680 credit score. The rate can increase after year 5.
Rockford Homes7/6 ARM with a lock of up to 12 months5.125% for 7 years, then adjusts every 6 months6.416%New to-be-built homes with more than $50,000 in options, offered instead of the $25,000 Flex Cash, through a Rockford preferred lender, for a limited time. Rockford's example: $650,000 price, 20% down, 760 credit score. The rate can increase after year 7.
Maronda Homes5/1 ARM, FHA 30-year, select move-in ready homes4.99% starting rate5.760%Tagged on select move-in ready homes at Autumn Grove, Walker Pointe and The Oaks, through Maronda's affiliated lender, RMC Home Mortgage. Maronda's example: 3.5% down, 640 credit score. No end date published. The rate can increase after year 5.
Ryan Homes3/1 ARM, FHA, rate bought down at a cost of 3.125% of the loan5.5% for 3 years6.100%Ryan's financing example at Rutherford Acres through NVR Mortgage: $389,990 price, 3.5% down, 60-day lock. The 5.5% rate costs 3.125% of the loan amount, and the rate can increase after year 3.
Ryan Homes3/1 ARM, FHA, rate bought down at a cost of 3.125% of the loan5.5% for 3 years6.112%Ryan's financing example at Davidson Towns through NVR Mortgage: $316,990 price, 3.5% down, 60-day lock. The 5.5% rate costs 3.125% of the loan amount, and the rate can increase after year 3.
Ryan Homes3/1 ARM, FHA, rate bought down at a cost of 3.375% of the loan5.99% for 3 years6.649%Ryan's financing example at Addison Farms Townhomes through NVR Mortgage: $282,990 price, 3.5% down, 60-day lock. The 5.99% rate costs 3.375% of the loan amount, and the rate can increase after year 3.
Ryan Homes3/1 ARM, FHA, rate bought down at a cost of 5.375% of the loan4.75% for 3 years5.554%Ryan's financing example at Cobblestone Towns (opening November 2026) through NVR Mortgage: $284,990 price, 3.5% down, 60-day lock. The 4.75% rate costs 5.375% of the loan amount, and the rate can increase after year 3.

Rates and APRs as published on each builder's website, checked October 22, 2026. Programs are offered by each builder's affiliated lender, not by The Wulf Collaboration or Coldwell Banker Realty, and usually require that lender. They apply to select homes, contract dates and closing dates, assume the credit score, down payment and loan amount in each builder's APR example, and are subject to credit approval. Adjustable rates can increase after the fixed period. Not an offer to lend. I confirm what's current before you sign anything.

A recent client

She walked into closing on a brand-new home for less than $5,000

She wanted a brand-new home and needed down payment assistance to get there. We got her approved for an Ohio down payment assistance program that works on new construction, negotiated $7,000 of her closing costs covered, and she walked into closing owning a brand-new home for less than $5,000.

The home
Brand-new construction
Down payment assistance
Approved
Closing costs covered
$7,000
Brought to closing
Less than $5,000

One client's experience. Every buyer's situation, program eligibility and builder offer is different, and nothing here is a promise of a specific result.

Down payment assistance

Assistance programs can work on a brand-new home

A lot of buyers assume assistance programs only apply to resale homes. In Ohio, many can be used on new construction too, alongside what the builder is offering. Each program has its own income limits, price limits and lender requirements, so the first step is a conversation with a lender who works with them. I'll introduce you to lenders I trust.

Ohio Housing Finance Agency

OHFA Down Payment Assistance

Statewide help toward the down payment and closing costs, paired with an OHFA first mortgage through an approved lender. OHFA lists newly built, move-in ready single-family homes as eligible. Income and purchase price limits apply.

Ohio Housing Finance Agency

Grants for Grads

An OHFA option for buyers who recently earned a college degree and are buying a home in Ohio. It runs through the same approved lenders and has its own guidelines.

City of Columbus

American Dream Downpayment Initiative

For homes inside Columbus city limits, which is not the same as a Columbus mailing address. New construction qualifies once the home has its final certificate of occupancy. Uses a City-certified lender.

Counties, nonprofits and banks

Other programs around Columbus

Franklin County has a program for homes outside Columbus city limits, and some statewide grants run through participating banks. Funding opens and closes during the year, so I check what's open when you're ready to buy.

How builder offers and assistance fit together

A builder's credit can usually go toward closing costs, and assistance can go toward the down payment, so the two often work side by side. Each loan type caps how much the builder can contribute, and neither pays cash back at closing. Some builder offers require the builder's own lender, which may not be approved for a given program. I help you sort that out before you sign.

Programs, limits and funding change and are subject to availability. Summarized from each program's public materials as of October 20, 2026. A participating lender confirms eligibility. This is not an offer to lend.

Before you visit a model home

The builder's team works for the builder

The sales team in the model is great at what they do, and their job is to sell the builder's homes. Having your own agent costs you nothing extra in most cases, and it puts someone on your side for the decisions that matter most.

Tell me before your first visit.

Most builders need your agent with you, or registered, at your first visit to the community. If you walk in on your own first, it can be hard to bring an agent in later. A quick text to 614-483-2044 before you go is all it takes.

  1. Register you at the first visit

    I set up the appointment, come with you, and make sure you're on record as my client.

  2. Compare communities and homesites

    Homesite premiums, which way the home faces, what's planned next door, HOA dues and what they cover.

  3. Work the builder's offer

    Closing cost help, design credits, rate buydowns. I know what each builder is offering this month and what's worth asking for.

  4. Review the builder's contract

    Builder contracts are written by the builder. We go through deposits, timelines, and what happens if dates move.

  5. Inspect during construction

    An independent inspector before drywall and again before closing, so problems get fixed while they're easy to fix.

  6. Walk the punch list with you

    The final walkthrough, then the warranty list before your first year is up.

Your hand-picked list

Tell me where you'd love to live

I'll put together a short list of new homes that fit, with current prices and what each builder is offering, and I'll reach out personally. No cost and no pressure either way.

Rather talk first? Call or text 614-483-2044 Or book 30 minutes on my calendar
Where would you love to live?
Want to tour a model home with me?

By sending this form you agree that Nick Wulf may contact you by phone or email about your home search. Privacy policy.

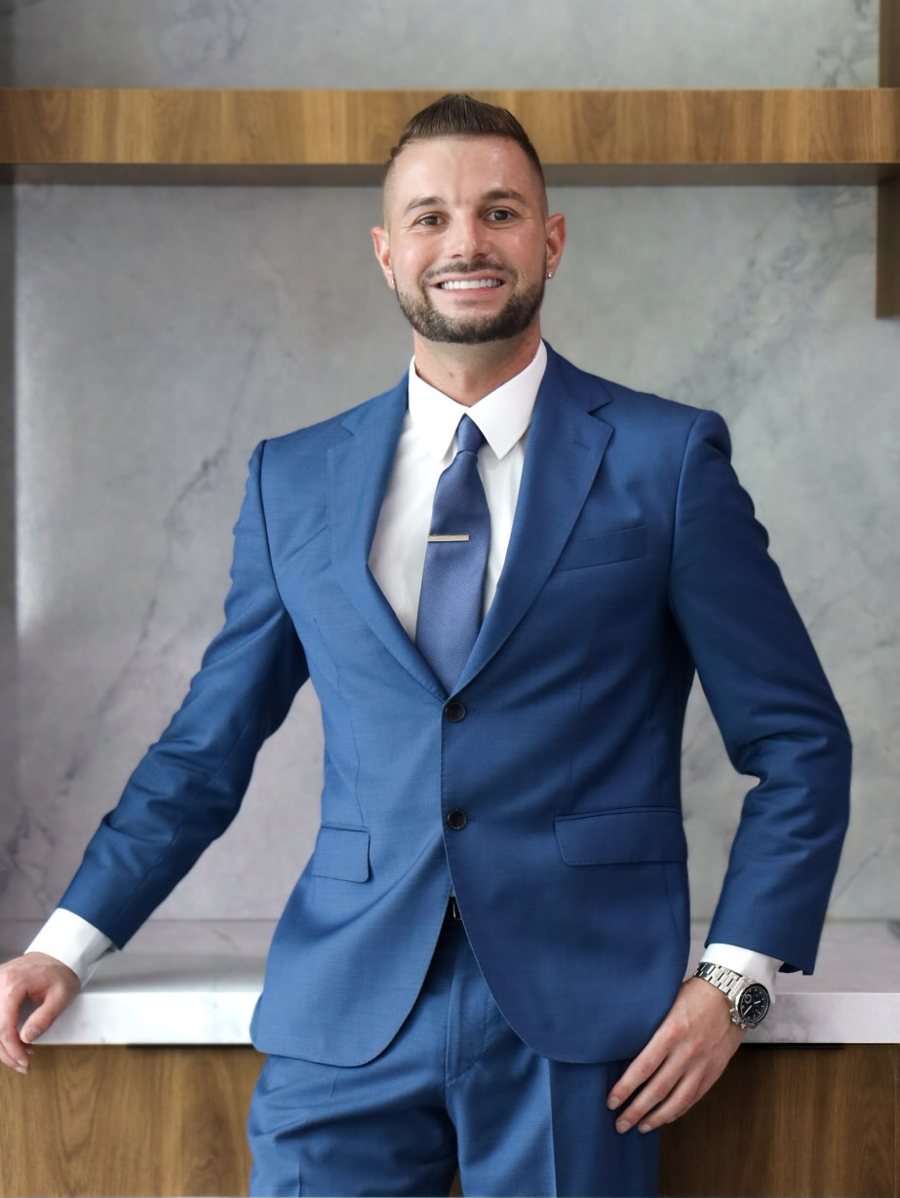
Nick Wulf

Your advisor

Nick Wulf

New construction looks simple from the model home. The details live in the homesite premium, the design center and the builder's contract, and that's where I spend my time for my clients. I walk these communities, I know the builders and their sales teams, and I know which questions to ask before anyone signs anything.

350+
Homes sold
$120M
In sales
8
Years
A vaulted great room with wood beams, a chandelier and a wall of glass to the back patio

Representative photo

Model home visits

See it in person, with me


Pick a community and a day. I'll set up the visit with the builder, meet you there and make sure you're registered as my client from the first step through the door.

Get my list Call